Automate your trading with AI.
Build quant strategies with AI, prove them on CME history, deploy to your prop firm.
A product scene. The prompt “Build an opening-range breakout on NQ that can pass a 50K eval.” goes to Quinn, which writes bot.py and backtests it on 2,750 NQ sessions (Jan 2016 – Oct 2026): net p&l $10,463, profit factor 1.07, win rate 49.4%, max drawdown $6,225, trades 1,906. Pass odds: Topstep 50K 30.3%, Tradeify 50K 35.6%, Lucid 50K 23.6% at 5 contracts. Hypothetical simulation from backtested results.
Hypothetical simulation from backtested results · drag to rotate
Build an opening-range breakout on NQ that can pass a 50K eval.
Trade the first 5-minute close outside the 9:30–10:00 range, stop at the other side, target 1.5R, one trade a day, flat by 3:55. Writing it now.
Wrote bot.py, 56 lines.
Backtested on 2,750 NQ sessions, Jan 2016 – Oct 2026.
Pass odds by firm, 2,000 simulated evaluations each:
1 contract: 9.0% pass · 5 contracts: 35.6%
At 5 contracts, 64.3% hit the floor first.
Want me to try a closer target, to see whether the odds hold up?
Ask Quinn to build or change the bot
Backtests are hypothetical results on historical data. Futures trading involves substantial risk of loss.
In the engine
- One-minute bars
- 21,938,051
- CME futures markets
- 6
- History since
- 2016
- Prop firms’ rules
- 19
Build. Test. Deploy.
From one sentence to a strategy trading your funded account.
- 01 · Build
Describe it. AI writes it.
Plain English in; a Python strategy on the qy engine out, rules you can read and own. Quinn writes it, you keep every line.
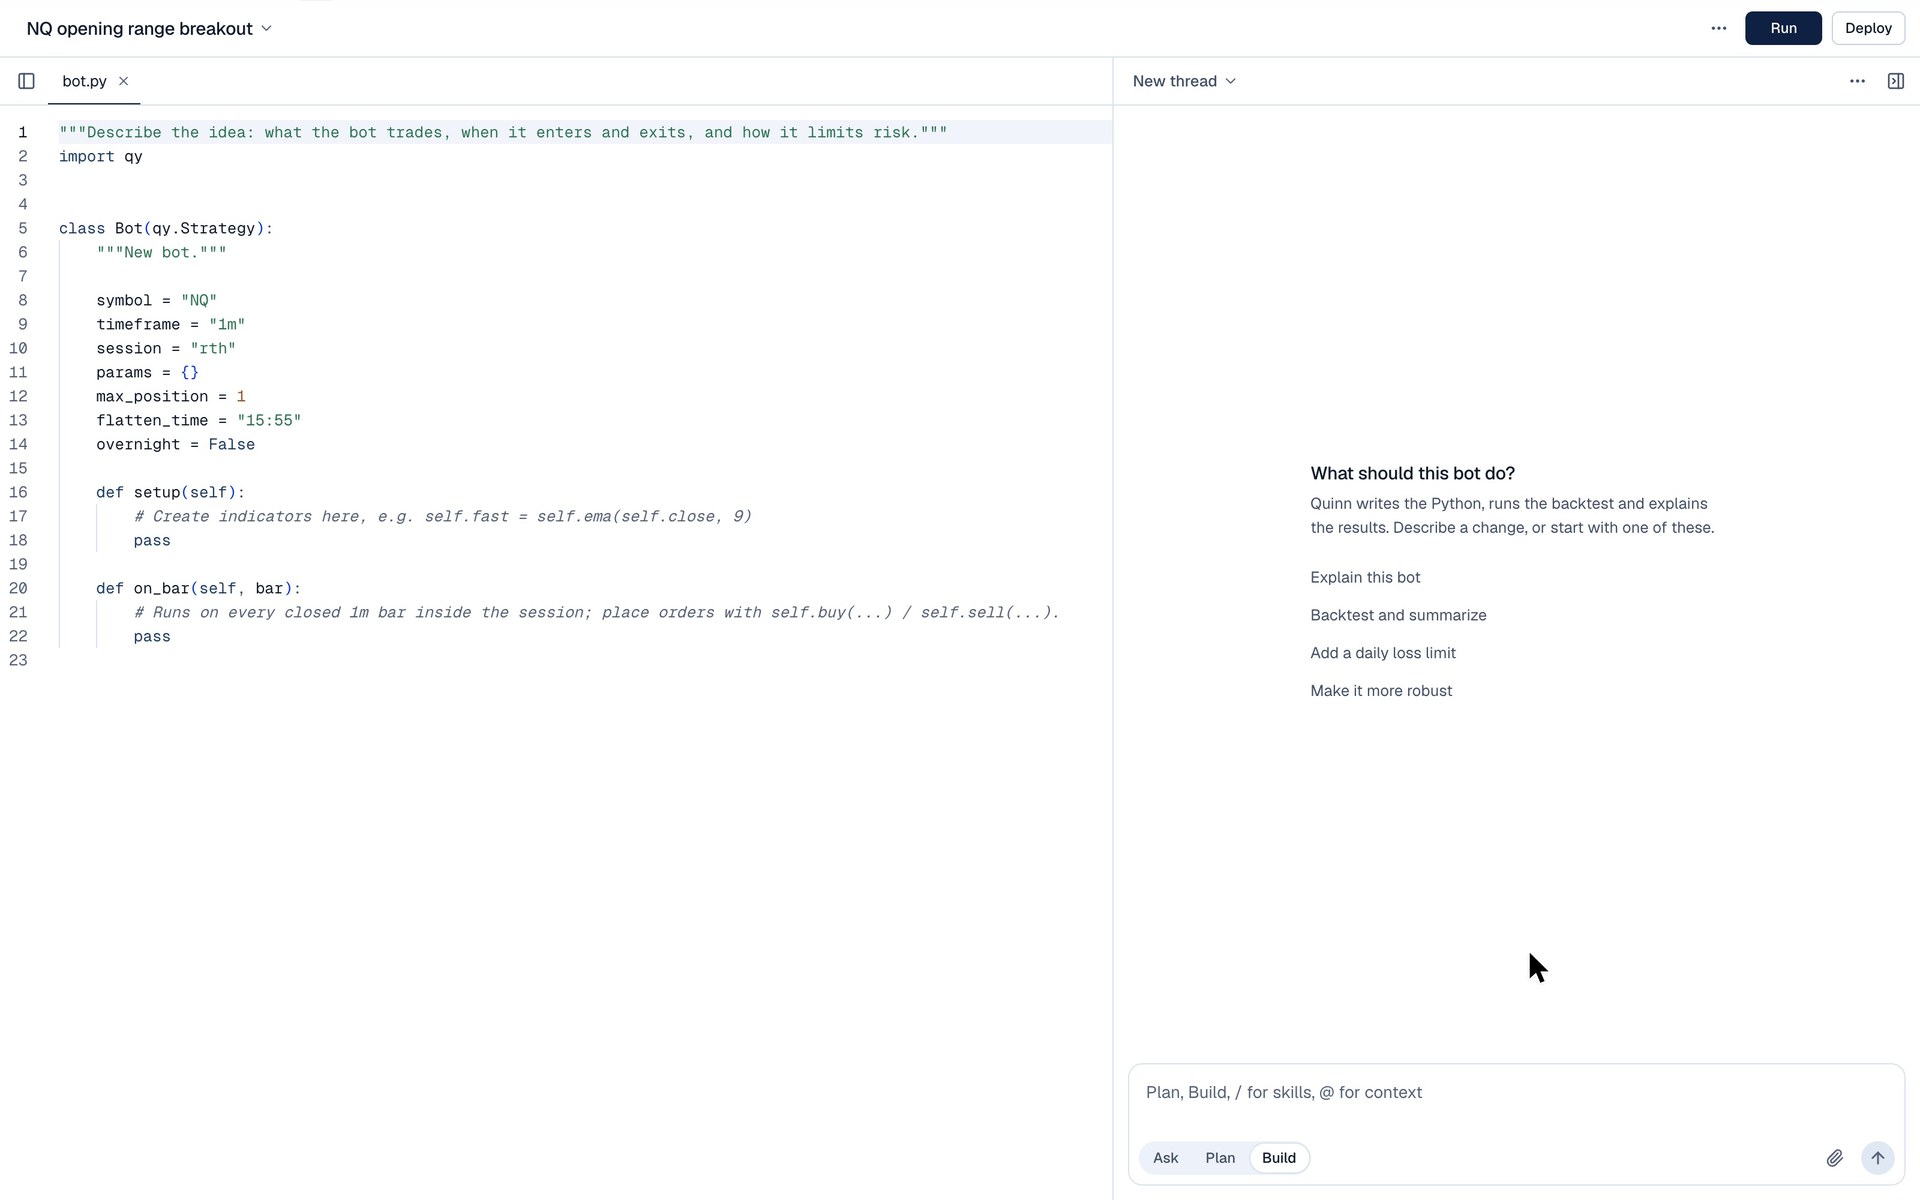
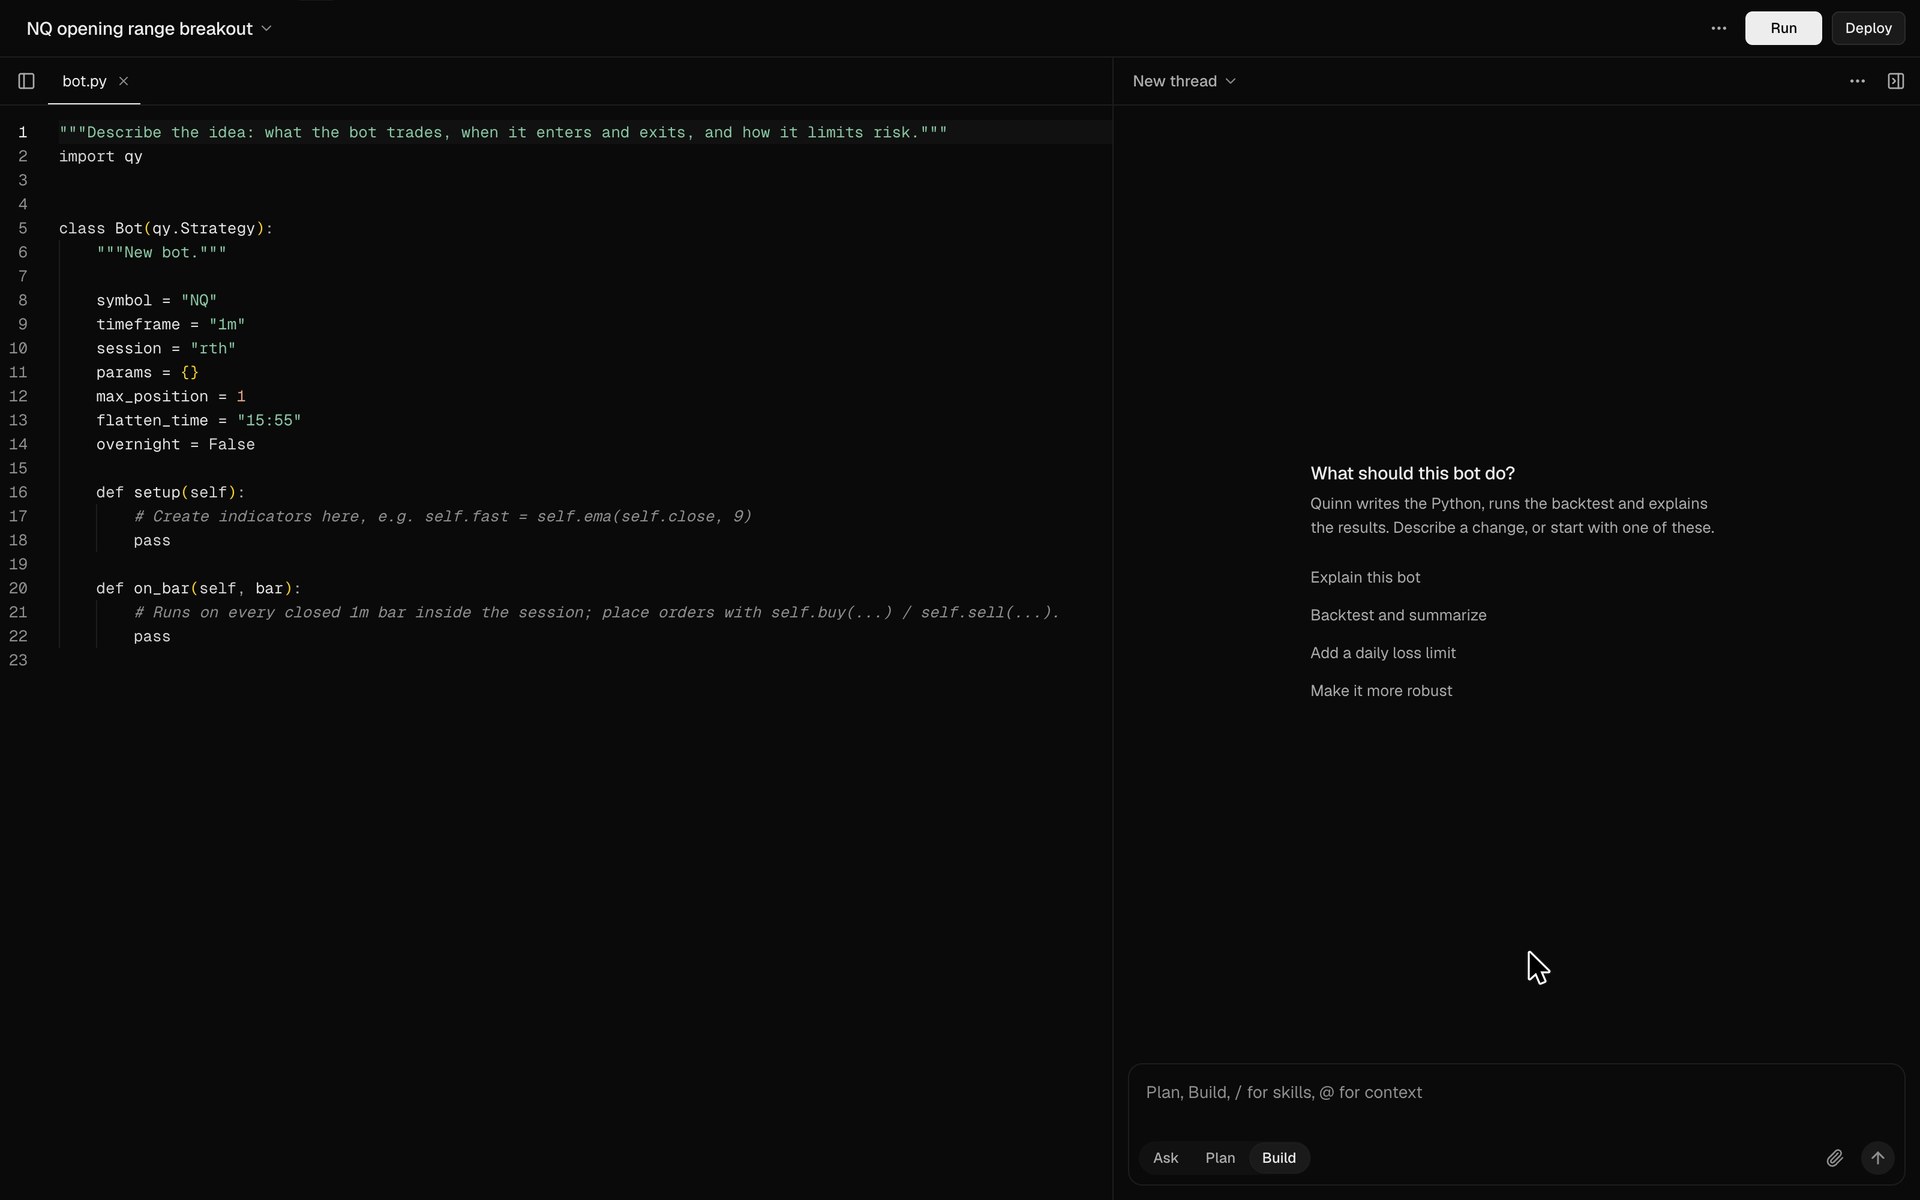
Recorded in the app: Quinn writing “NQ opening range breakout” (MNQ, 5-minute), its own take on the strategy above.
- 02 · Test
Prove the edge.
Ten years of 1-minute CME data, costs on every fill, an out-of-sample run and the odds of passing your firm’s evaluation.


The app’s phone layout: pass odds for the opening-range-breakout starter on a generic 50K evaluation, from its backtest of Jan 2016 – Oct 2026. Hypothetical simulation.
- 03 · Deploy
Connect your prop firm.
Deploy through TradersPost, PickMyTrade or your own webhook, with the firm’s limits checked on every order.


The opening range breakout from the top of the page, deployed to paper: its live monitor on the app’s simulated feed (replayed history).
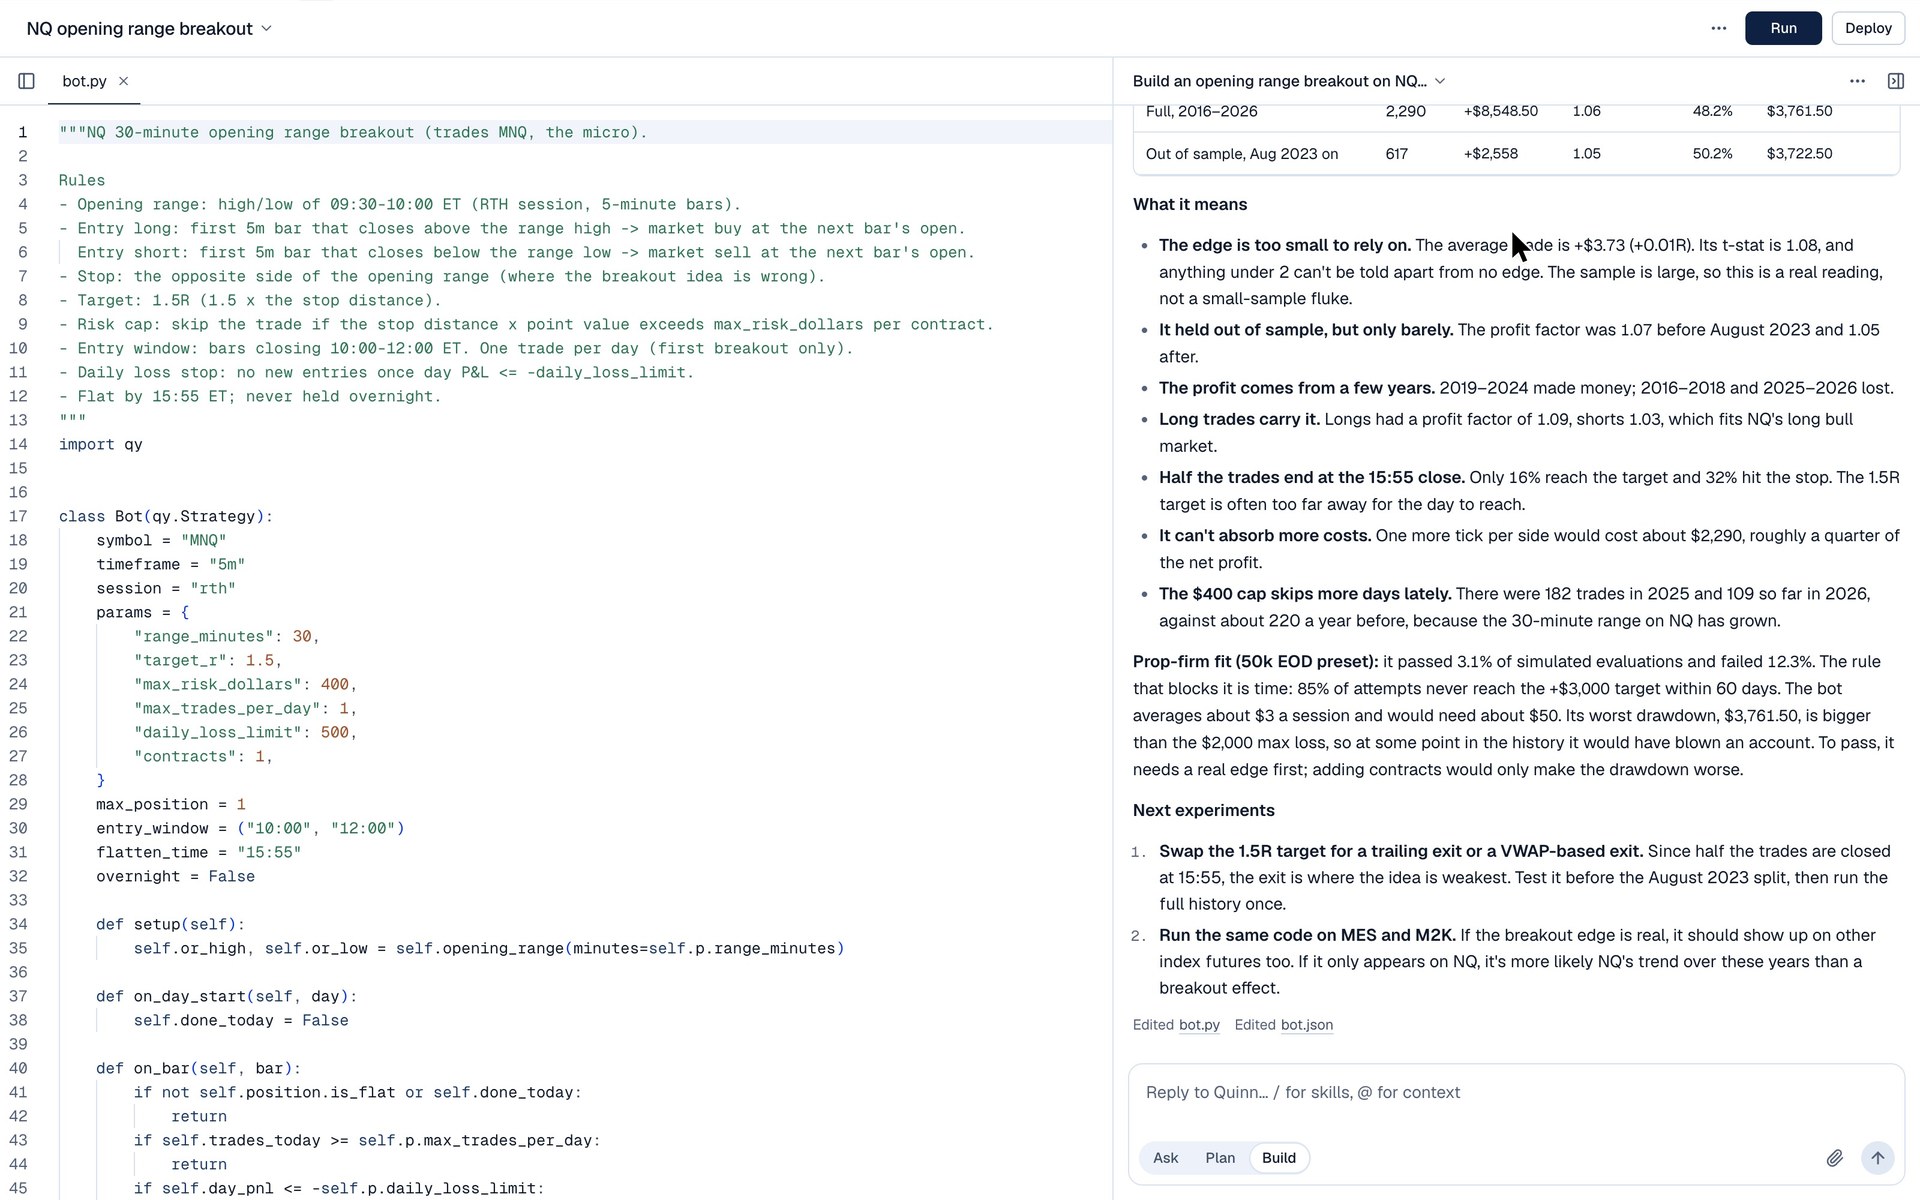
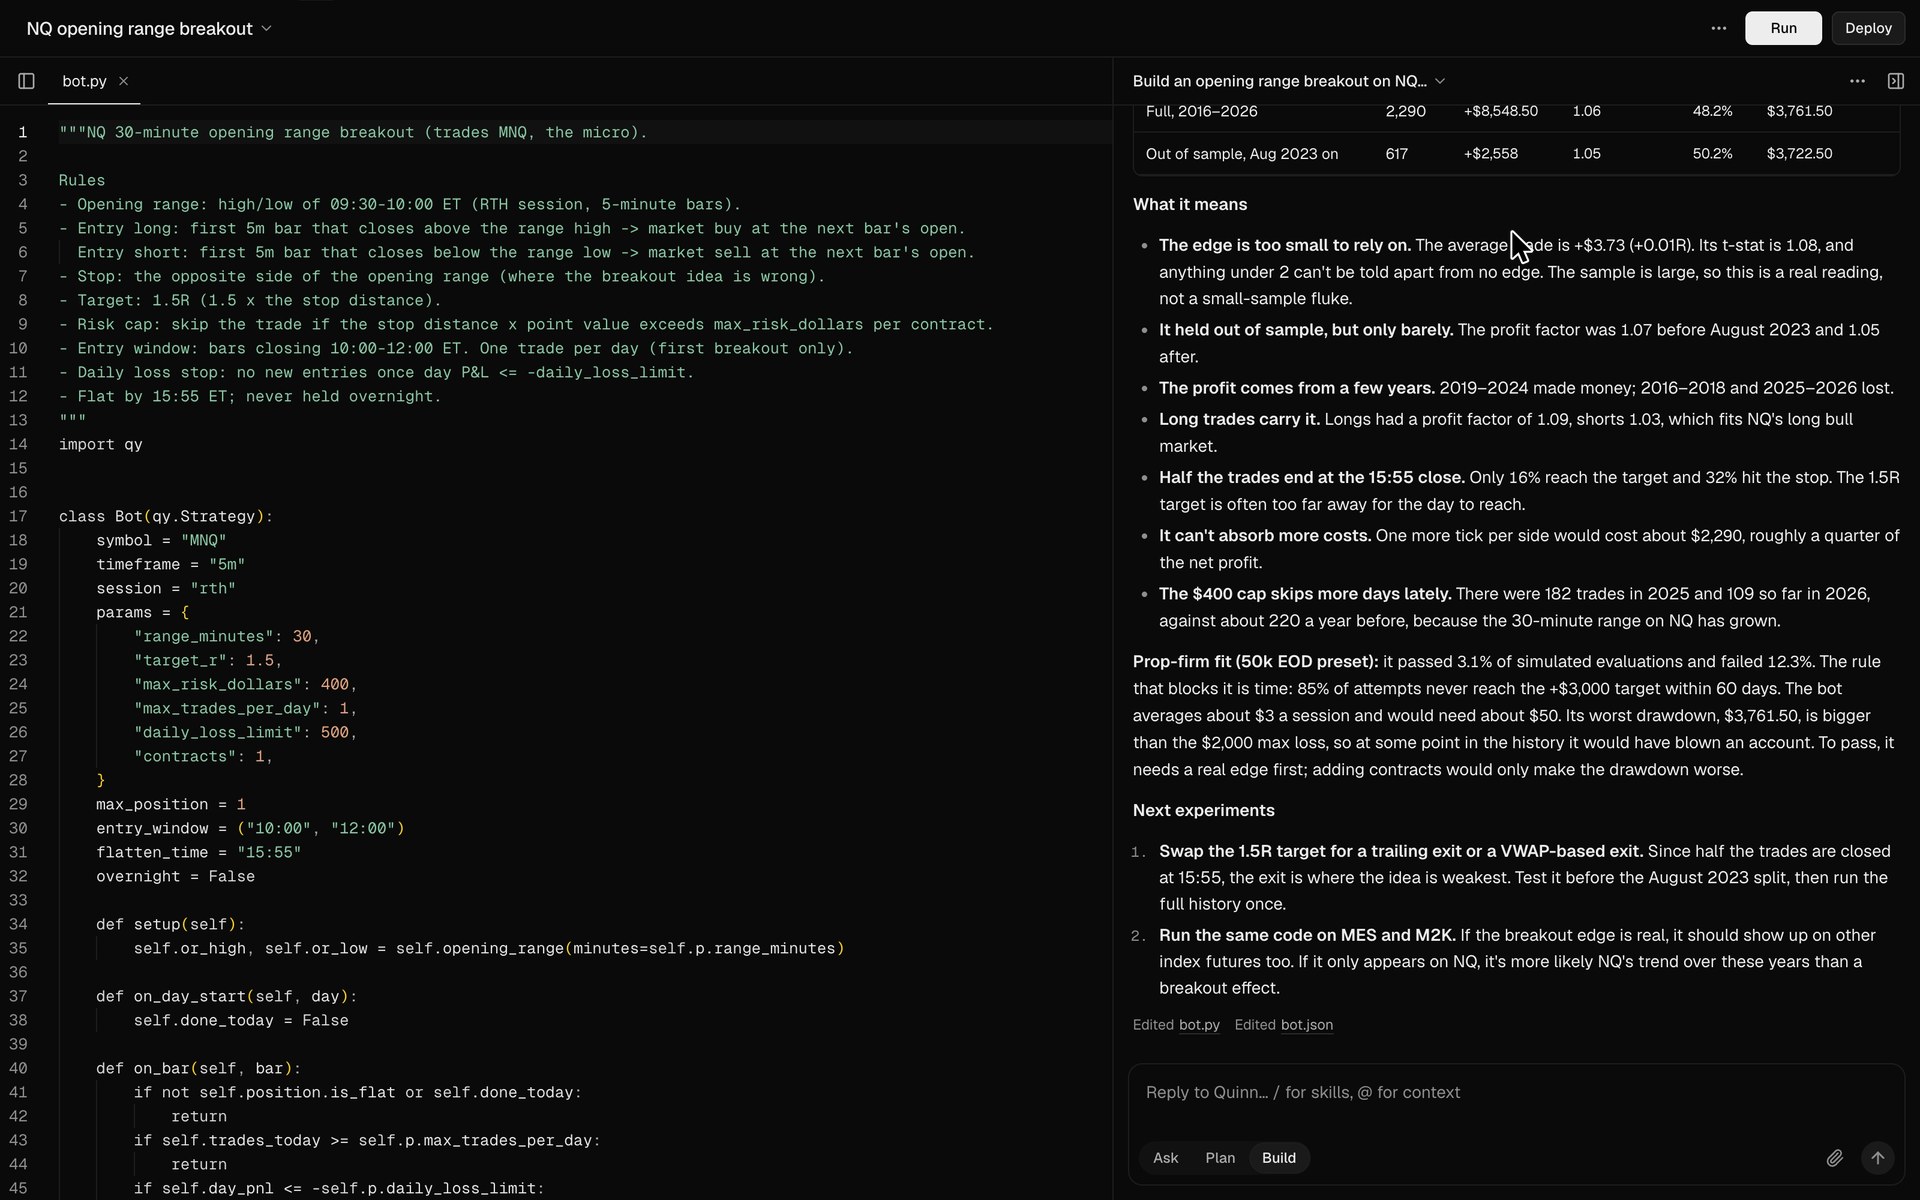


Recorded in the app: Quinn writing “NQ opening range breakout” (MNQ, 5-minute), its own take on the strategy above.
Proof before you pay the fee.
One real backtest on ten years of CME data, view by view.
Equity, drawdown and the stats that matter
Net P&L, profit factor, win rate, max drawdown, expectancy in R and Sharpe; the equity curve with its drawdowns; pass odds for your plan.


One backtest in the app: the opening-range-breakout starter, MNQ, 5-minute bars, on 1-minute NQ history from CME (Databento), Jan 2016 – Oct 2026, commission and slippage included. Hypothetical backtest results. Simulated performance has inherent limitations, doesn’t represent actual trading and was produced with hindsight; past performance doesn’t guarantee future results.
Real CME data, minute by minute.
One-minute bars for six futures markets from CME Globex via Databento, behind every backtest and every chart.
- ES7,754.00E-mini S&P 500+0.22%
3,777,725 bars since 2016
- NQ29,566.25E-mini Nasdaq-100+0.44%
3,746,019 bars since 2016
- YM52,516.00E-mini Dow+0.14%
3,761,385 bars since 2016
- RTY2,867.60E-mini Russell 2000+0.26%
3,079,936 bars since 2017
- CL102.77Crude oil+2.70%
3,794,609 bars since 2016
- GC4,034.30Gold−0.23%
3,778,377 bars since 2016
Each market’s latest regular session (2026-10-29), 5-minute closes, 9:30 to 16:00 ET. CME Globex data via Databento.
Connect your prop firm.
Deploy in minutes: QuantReplay’s guard checks every order against the firm’s daily loss, drawdown and size limits.
Connect your prop-firm account
TradersPost or PickMyTrade to your Tradovate-based prop account, your own webhook, or paper.


Bridges today
Native Tradovate is built but off by default and untested with live accounts; bridge fills are marked Estimated.
Rules from our catalog
Sourced, dated policies; firms that ban bots are blocked, conditions are confirmed first.
Topstep on your own computer
Topstep requires orders from the trader’s own computer, never a server.
Every firm’s rules, built in.
Sourced bot policies for 19 firms; QuantReplay blocks the 6 that ban bots.
- Apex Trader Funding
- Topstep
- Tradeify
- MyFundedFutures
- FundedNext Futures
- Take Profit Trader
- Elite Trader Funding
- Bulenox
- TradeDay
- Alpha Futures
- Lucid Trading
- Funded Futures Network
- Earn2Trade
- Funded Futures Family
- FTMO Futures
- Top One Futures
- Phidias Propfirm
- Goat Funded Futures
- AquaFutures
Topstep
Allows bots through its TopstepX API add-on when every order comes from your own computer; Live Funded accounts can’t use the API.
- Bots in evaluation
- Allowed with conditions
- Bots when funded
- Allowed with conditions
- Conditions
- API add-on; your own computer; not Live Funded
- Profit target
- $3,000
- Max loss
- $2,000, end-of-day trailing (stops at $50,000)
- Daily loss limit
- $1,000, pauses the day
- Max size
- 5 minis or 50 micros
- Consistency
- Best day ≤ 55% of total profit
From our research, not from Topstep. Rules change; verify on Topstep’s site before you trade. Topstep site
Topstep. Bots in evaluation: Allowed with conditions. Bots when funded: Allowed with conditions.
All 19 firmsCharts: trade the past.
Watch today’s market live, then paper trade any past session bar by bar, with your strategy on the chart.
The market right now
Live chart by TradingView. TradingView’s embedded charts don’t carry CME futures, so this shows the S&P 500 and Nasdaq 100 that ES and NQ track.
Charts, replaying a session


CME data via Databento: the NQ session of Thursday, 2026-10-22 in the app, 5-minute bars at 5×, with the opening-range bot’s trade.
Start free on paper.
Preview pricing · not on sale yet
Free
Build, test and paper trade.
$0Upgrade when you go live
Start free- Paper deployments
- 25 backtests a month
- Limited Quinn usage
- Charts: paper trading on history
Pro
For taking a bot live on a prop account.
$49/moBilled monthly
Start building- Everything in Free
- Unlimited backtests
- Quinn usage included
- 3 live webhook deployments
Desk
For several accounts and several bots.
$149/moBilled monthly
Start building- Everything in Pro
- 15 live deployments
- Native broker adapters as they launch
A preview of QuantReplay’s launch pricing. Paid plans aren’t on sale yet; final prices and Quinn usage limits will be published here before they are. Prop-firm evaluation fees and bridge subscriptions (TradersPost, PickMyTrade) are billed by those companies.
Straight answers.
What traders ask before they let an AI bot near a funded account.
6 of the 19 firms we track, including Apex, TradeDay and Alpha Futures, prohibit automation. Topstep allows it through its API Access add-on but requires orders from your own computer, not a VPS or remote server, and its Live Funded accounts can’t use the API.
Every firm’s policy is shown with its sources and the date it was last reviewed. We block deployments a policy prohibits and ask you to acknowledge anything conditional or unclear. Always confirm with your firm.
Today: Paper, TradersPost, PickMyTrade and any custom webhook that accepts JSON, and deploying takes minutes once the account is connected. Through the bridges you can reach Tradovate-based prop accounts. They can also reach TopstepX, but Topstep’s rule that orders come from your own device makes a bridge there an open question, so we ask you to confirm with Topstep first. Bridges don’t report fills back, so those positions are labeled Estimated. The connection test checks the webhook URL’s format only: TradersPost has no dry run, so nothing is sent.
Native Tradovate and ProjectX connections are built from the brokers’ API documentation but not yet tested against live accounts. They’re off unless the server sets ENABLE_NATIVE_BROKERS=1, and Tradovate’s personal API keys reportedly can’t reach prop evaluation accounts.
Yes. Backtests, Charts and the numbers on this page come from 1-minute CME history via Databento: 21,938,051 bars across ES, NQ, YM, RTY, CL, GC, since 2016 (RTY since 2017). Micros trade on the full-size series. A self-installed copy starts with synthetic sample data until you set your own Databento key and run npm run data:databento.
Backtest results are hypothetical: how a strategy’s rules would have traded the past, with commission and slippage, not what they will do. The live chart is TradingView’s. Pass odds are simulated from the backtest’s own trading days, and the deploy monitor shows a paper deployment on the simulated feed; both are labeled that way. A live Databento feed for deployments is built but not yet tested against the live service; paper deployments can run on a simulated feed that replays history, always labeled Simulated feed.
The risk guard checks every entry against your limits (max contracts, daily loss, trailing drawdown, trading window and flatten time) and blocks any entry whose worst-case stop-out would cross one.
If a fill or a fast market trips a limit anyway, the guard flattens the position and locks the deployment until the next session starts at 18:00 ET. Exits are never blocked.
Today the runner runs on the computer where QuantReplay is installed: a separate process that keeps each bot going and checks every order before it leaves. Topstep requires orders from your own computer, so a Topstep deployment must always run there.
No. They are a simulation: your backtest’s trading days, resampled through the evaluation’s rules thousands of times. They show how past results interact with the rules, not what will happen next, and a small sample makes them unreliable.
Yes. A bot is a plain Python file, a qy.Strategy class, plus a small JSON manifest. You can read, edit and copy every line.
There are no user accounts yet. Bots are stored as files in the app’s data folder on the machine where QuantReplay runs, and we don’t publish, sell or trade them. When you chat with Quinn, your messages and the relevant code are sent to Anthropic’s API to generate replies. The privacy policy (draft) has the details.
Paid plans aren’t on sale yet. The refund policy will be published in the terms before they are.
Automate your trading.
Free in the preview
Build a strategy, test it on CME history and deploy it to paper. Connect your prop-firm account when the evidence holds up.
- Bot Studio with Quinn
- Charts: paper trading on real history
- Paper deployments
- 25 backtests a month
Preview pricing, not on sale yet.